 News body NBDA seeks journalistic exemption under digital data rules
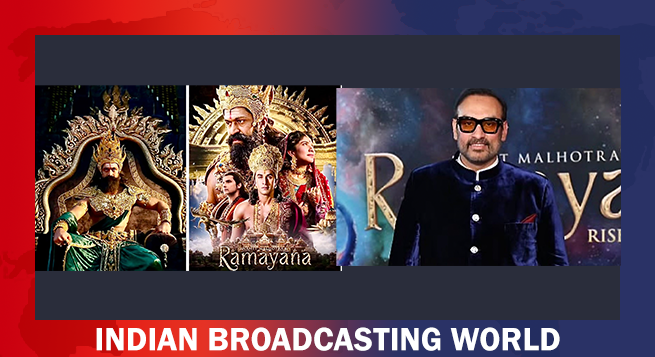 ‘Ramayana’ producer Malhotra likens film to ‘Avatar’, ‘LOTR’, ‘Odyssey’
 Bombay HC protects ‘Ramayana’ from piracy
 CEO Jassy says Prime Video gains profit; bullish on ad momentum
 JioStar Q2 revenue up 10.1% to Rs 6,806cr. despite weak ad environ
 Google brings AI Mode ads to India, 9 other markets
 Tata Play appoints Abhishek Pathak as Chief Content Officer
 Bhuvan Bam announces ‘Dhindora’ S2 release date
 Apple TV announces new series ‘Lenni’ starring Toni Collette
 ‘The Traitors Telugu’ heads into finale with six players
 JD Majethia explores AI storytelling with ‘Tulsi Hai Na’

The Board of Control for Cricket in India (BCCI) has sought the Supreme Court view on whether its sale or grant of media rights qualified as taxable “franchise services,” therefore subject to service tax.
The issue arose after the Bombay High Court last year asked the cricket body to approach the Supreme Court to determine whether service tax can be levied for services rendered by the cricket board following agreements signed with MSM Satellite (Singapore) Pte Ltd and World Sport Group (India) in 2008 and 2009 in respect of telecast of Indian Premier League (IPL) matches being played in India, The Economic Times reported.
A Bench led by Chief Justice DY Chandrachud sought response from the Finance Ministry and the Commissioner of Service Tax, Mumbai, on the BCCI’s appeals against a demand for payment of service tax to the tune of around ₹250 crore, including penalty.
Challenging a part of the Customs, Excise & Service Tax Appellate Tribunal’s 2018 order that ruled against it, BCCI said its grant of media rights does not amount to providing of “franchise services” as the key ingredients to qualify as these services are not satisfied in its case.
BCCI is not granting the broadcasters any representational rights nor the latter are performing any output services or undertaking any activity which can be identified with the cricket body, senior counsel Arvind Datar told the apex court.