 Without naming Musk, RIL says it welcomes satcom competition
 Akash Ambani banks on selling more services to up revenue
 Sunil Mittal says OneWeb ahead of Musk in Indian approval queue
 Murugan resigns from Cabinet as Mos MIB & Rajya Sabha
 Broadcasters flag HD-SD conversion, satellite spectrum concerns in submission to MIB on telecom rules 2026
 Eros Music Worlds releases new Navratri songs every day
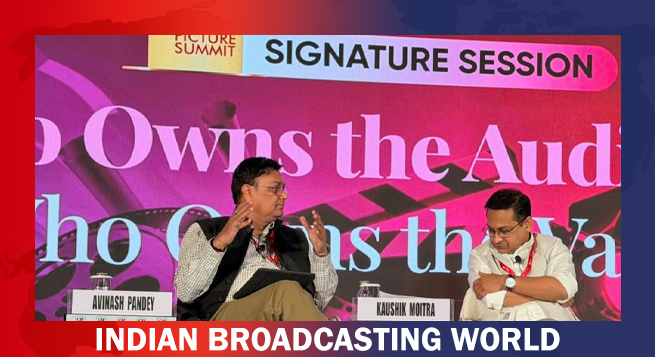 IBDF’s ’ Pandey flags audience trust, measurement for media growth
 Meher Bajwa joins NDTV Good Times as Editor
 India ‘26 BO hits Rs.11,000cr in Sept.; ‘Mirzapur:The Movie’ leads
 Netflix’s ‘Akka’ teaser unveils Keerthy Suresh, Radhika Apte’s gangster rivalry

By Elara Caps
Zee Entertainment (Z IN) reported revenue of INR 18,457mn, up 4 percent YoY, on low base, and down 20.5 percent QoQ, down 8 percent vs pre-COVID levels to INR 18.5bn, in line with our estimates, affected by FTA withdrawal (Zee Anmol) and lower ad spend by brands due to weak macroeconomic conditions.
The company reported an EBITDA of INR 2,358mn, down 31 percent YoY, and an EBITDA margin of 12.8 percent, down 660bp YoY and 820bp QoQ, primarily due to weak revenue growth and continued investment in the digital business. Reported PAT stood at INR 1,066mn, down 48.9 percent YoY, on the back of lower revenue growth during the quarter.
Z is estimated to report an ad revenue CAGR of 7.5 percent over FY23-25E, negatively affected by H1FY23,which has seen a sharp negative impact on ad spend.
This was due to:
1) RM inflation pressure on various business verticals (FMCG & auto)
2) the shift of Zee Anmol from FTA to pay; we estimate ad revenue for Z to revert to pre-COVID levels by FY24 (105 percent recovery rate vs FY20). In terms of subscription revenue too, concerns persist as there is still uncertainty over implementation of NTO 2.0; ARPU remains flat and there are concerns over the shift of viewership toward digital (early chord-cutting trends). Further, challenges persist on profitability too as EBITDA margin is estimated to be in the band of 16-23 percent over FY23-25, due to investments in digital offerings and lower subscriber revenue growth; growth momentum on digital (Zee5) is estimated to be 20 percent over FY23-25; however, losses may magnify YoY due to heavy investments in technology and content (current annual loss of INR 9.4bn basis Q1FY23). Merger with Sony remains to be a key monitorable, which will drive synergy and valuation multiple upgrade; we await NCLT approval for the merger.
Valuation: Z is currently trading at an inexpensive valuation of 23.5x FY23E earnings and 17.6x FY24E earnings. The stock has moved up a mere 4 percent over the past three months, as approvals on merger have taken time and the same has been an overhang. We pare down our revenue estimates by 2.1 percent for FY23 and 2.4 percent for FY24 after factoring in the negative implications of ad spend in H1FY23 and lower subscriber revenue; our earnings estimates cut was due to lower revenue on subscription and investment in the digital businesses. We reiterate Buy with a lower TP of INR 415 from INR 450 based on a SOTP method. We assign 19x (from 20x) one-year forward P/E for the broadcasting business, backed by synergies post-merger and 4.5x (from 5x) EV/sales for the digital business, as the digital OTT market in India is estimated to grow in the healthy double-digits.