 Uday Shankar: Indian M&E sector needs policy support to compete globally
 Guest Column: STB evolves from decoder to connected entertainment
 Meta says expanded AI sweep of ads linked to child abuse in India
 With WBD merger closed, Skydance is a Hollywood giant
 TRAI flags mixed 2025-26 trends: DTH shrinks, telecom base expands
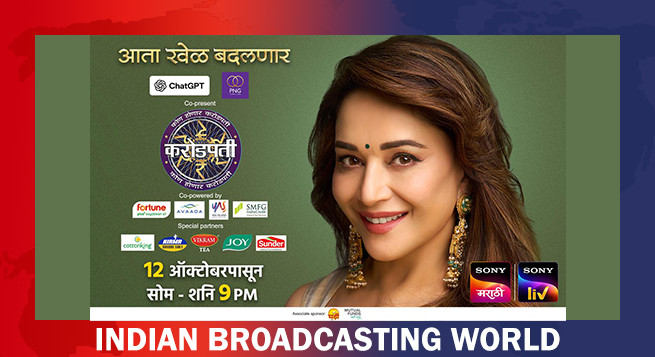 Sony Marathi’s ‘Kon Honar Crorepati’ signs up major brands
 Prime Video unveils ‘Apocalypse Z: New World’ trailer
 Netflix shows and films bring readers back to books
 Prime Video to premiere crime drama ‘Chaar Yaar’ on Oct 23
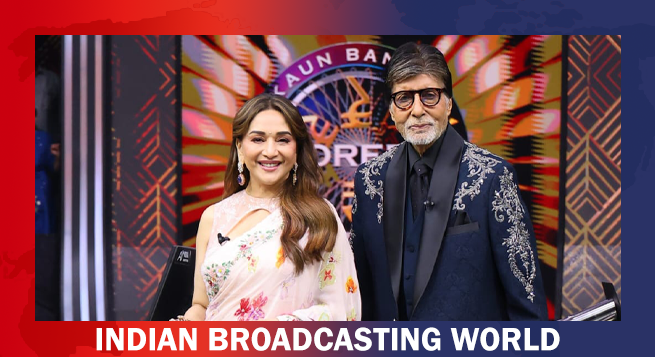 Madhuri Dixit shares late mother’s life lessons on ‘KBC’ 18

By Karan Taurani @ Elara Capital
Broad-based profitable growth
Revenue growth –Strong digital performance
TV Today Network’s (TVTN) Q3 revenues grew 15.4% YoY (up 16% versus pre-COVID levels and 14.2% QoQ) to INR 2,580mn (Elara E: INR 2,498mn), better than estimated. This was largely led by healthy performance in the digital segment (contributes 21% to revenues); TV broadcasting segment (contributes 77% to revenues) grew 6% YoY to INR 1,978mn. Overall, Q3 EBITDA margin declined 140bps YoY to 33.2% (up 690bps QoQ), mainly on account of production expenses that rose 38% YoY, resulting in a margin decline. Q3 PAT rose 12% YoY to INR 615mn (up 64% versus pre-COVID levels and 31% QoQ), led by strong revenue growth. Depreciation and interest expenses were largely stable.
Compelling digital proposition to drive growth
We estimate TVTN to post FY21-24E revenue CAGR of 15% in the TV segment given: 1) market leadership in the Hindi news genre, 2) news genre being the least impacted by digital ingress due to live content and 3) little/no negative impact of NTO 2.0 given strong recall. The Digital segment is the silver lining, with its revenue contribution seemingly spiking 450bps in the next two years to 24% through to FY24E (29% revenue CAGR). This may be led by: 1) a platform-agnostic approach, 2) broad-based growth in own app, YouTube and social media and 3) increased penetration and consumption-led growth for video content in India. The digital segment remains highly profitable with ~25% EBIT margin due to the platform-agnostic approach and better segmental growth. This should aid overall profitability. Also, TVTN enjoys a healthy cash balance of ~INR 7.5bn, which may be used for higher dividend pay-out/acquisition. Also, there is potential for sharp growth in FY25, led by general elections (which leads to ~5-6% higher growth).
Valuations: Reiterate BUY; TP raised to INR 610
We largely retain estimates, and value TVTN on SOTP, assigning a P/E of 10x one-year forward to the broadcasting segment, factoring in converging growth of traditional media and highly fragmented news segment. We assign a market cap/sales multiple of 4x one-year forward to the digital business propelled by: 1) scale (24% revenue contribution, much higher than other broadcasters) and 2) a platform-agnostic approach that caps content costs and drives profitable growth. Our SOTP March 2023E TP is raised to INR 610 (from INR 400 based on 10x P/E for TV broadcasting and 4x MCAP/sales for digital segment, after factoring in healthy cash in hand – Maintain BUY